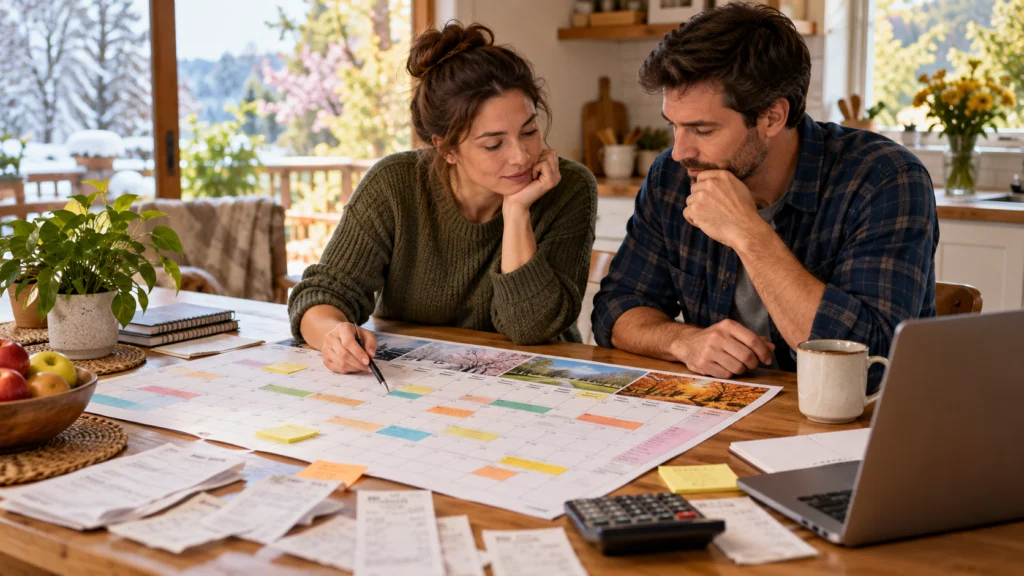
Seasonal income can make an annual total look adequate while leaving difficult gaps between pay periods. Bills continue when work slows. A useful plan shows both the year’s resources and the dates when money is available.
Separate confirmed income from expectations
Record known work periods and actual payment timing. Mark uncertain hours, contracts or bonuses separately. A best-case season should not become the only basis for year-round commitments.
Use the history you have without pretending next year must repeat it. Changes in work, costs or household needs can alter the pattern. Build a cautious scenario alongside the expected one.
| Part | Record | Planning question |
|---|---|---|
| Income periods | Expected and confirmed receipts | When does money actually arrive? |
| Year-round bills | Necessary recurring commitments | What continues in quieter months? |
| Irregular costs | Known annual or seasonal payments | Which reserve funds them? |
| Uncertainty | Lower or later income scenario | What changes before a shortfall? |
Give reserves separate purposes
Money held for next month’s rent is not the same as surplus available for an optional purchase. A reserve for known annual bills differs from an emergency fund. Clear labels prevent the same balance being assigned several jobs.
If saving gradually is difficult, start with a workable amount and review it in stronger periods. Do not automate transfers that repeatedly create an essential-bill shortfall.
- Put payment dates beside income estimates.
- Protect necessary costs through quieter periods.
- Keep known bills separate from emergency needs.
- Review the forecast when the work schedule changes.
Respond before the gap arrives
A forecast can show when optional spending needs to wait or when a provider should be contacted about a payment concern. Do not assume a new loan or future strong month will automatically repair every recurring mismatch.
FCAC recommends tracking income and spending and revising the budget against reality. For seasonal work, that means reviewing timing as well as totals. Seek qualified assistance if necessary commitments remain unaffordable. Keep the expected and actual payment dates together so a delayed receipt is not silently removed from the record.
Questions and answers
Is annual income enough to judge affordability?
No. Timing matters when bills fall due before receipts arrive.
Should every strong month be treated as surplus?
Not before future necessary costs and reserves are considered.
Can last season’s earnings be guaranteed for the next one?
No. Use history as context and keep uncertainty explicit.
Sources: canada.ca.